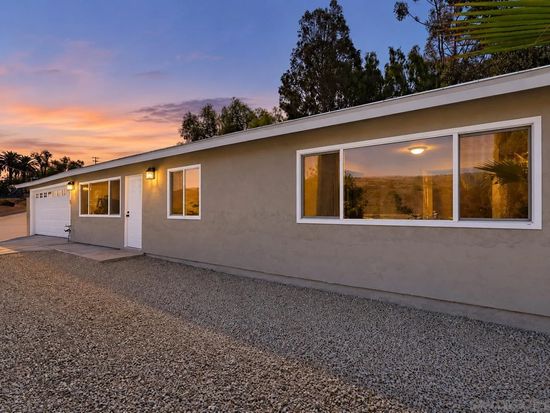
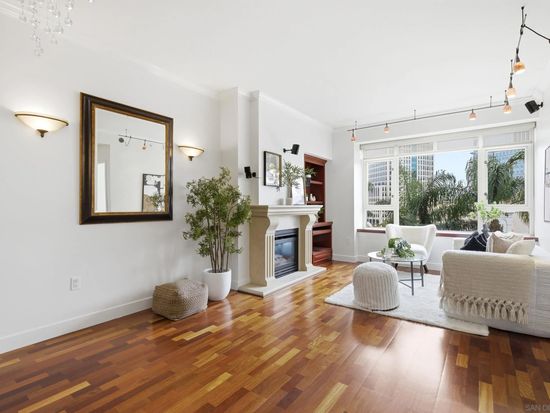
Compare conventional financing; eligible military buyers can also explore VA, subject to condo project approval. Include HOA dues in the budget.
Illustration: 5% down = $25,650; base loan ≈ $487,350. This falls within the standard conforming loan-size range. Eligibility still requires lender review.
Compare conventional high-balance financing at a smaller down payment, or VA for an eligible owner-occupant. Verify condition and permitted improvements.
Illustration: 5% down ≈ $46,250; base loan ≈ $878,749. This falls within San Diego County’s 2026 high-balance conforming loan-size range.
Jessica Rocha works with San Diego buyers, sellers, and people relocating to the region. Her perspective combines real estate investment experience with a background in business ownership.
Start with what matters: your timeline, your comfort level, and the way you want to live. The right conversation can bring your next step into focus.
Perspective. Communication. A personal connection.
01
An investment perspective
Jessica’s background in property investment and business ownership brings an additional lens to conversations about condition, usability, and long-term ownership.
02
English & Español
Discuss your priorities in the language that feels comfortable. Clear communication helps make a complex move feel more manageable.
03
A move shaped around you
Her public specialties include relocation and first-time buyers. Start with your timeline and preferences, then discuss a practical search and purchase plan.
Five more homes to explore
Different homes. One remarkable city.
Additional San Diego listings across several price points. These properties are listed by the brokers credited below and are separate from Jessica’s featured collection.
Compare conventional high-balance financing and eligible VA financing. Confirm renovation permits, property condition, and intended occupancy with your lender.
Illustration: 5% down ≈ $50,000; base loan ≈ $949,999. This falls within San Diego County’s 2026 high-balance conforming loan-size range.
Jumbo is the conventional starting point with 20% down at this price. Eligible VA buyers can also request a lender review; larger loans may have stricter standards.
Illustration: 20% down = $459,000; base loan ≈ $1,836,000. This exceeds San Diego County’s 2026 one-unit conforming loan limit.
Listed by Keller Williams Realty · MLS #260024300
Listing snapshot: October 15, 2026. Confirm price and status.
Financing depends on more than price.
These examples are starting points, not individualized recommendations.
Your down payment, credit, income, occupancy, property condition,
condo eligibility, and lender guidelines determine the appropriate options.
Illustrations exclude closing costs, reserves, mortgage insurance,
and VA funding fees. VA is only available to eligible borrowers
and qualifying properties.
2026 one-unit conventional limits used here:
$832,750 baseline and $1,104,000 for San Diego County.
The limit applies to the loan amount, not the purchase price.
FHFA loan-limit source ↗
Property details are a manually curated October 15, 2026 snapshot,
not a live IDX feed. Review the linked listing for current information.
A city to make your own
More room for the life you want.
Waterfront walks, neighborhood cafés, outdoor afternoons, and a city full of different ways to feel at home. Discover what makes San Diego worth considering.
Beaches, bays, parks, and trails make it easy to build outdoor time into your routine. Explore the places you would actually use during an ordinary week.
02
Neighborhoods with character
From downtown’s urban rhythm to coastal streets and inland communities, compare settings based on your own priorities, commute, and housing budget.
03
Culture in your everyday
Balboa Park, dining, live performances, and waterfront destinations offer plenty to explore. Find the balance between an active calendar and a quieter home base.
For eligible buyers, VA financing can help preserve savings and avoid monthly mortgage insurance. Compare the complete costs with a mortgage professional.
Low upfront cashA down payment may not be required, subject to entitlement, appraisal, and lender requirements.
No monthly MIVA loans do not require monthly mortgage insurance. Funding fees and other closing costs may still apply.
More to compareAsk about eligibility, full versus remaining entitlement, condo approval, and your complete cost to close.

 Jessica’s Zillow collection
View on Zillow ↗